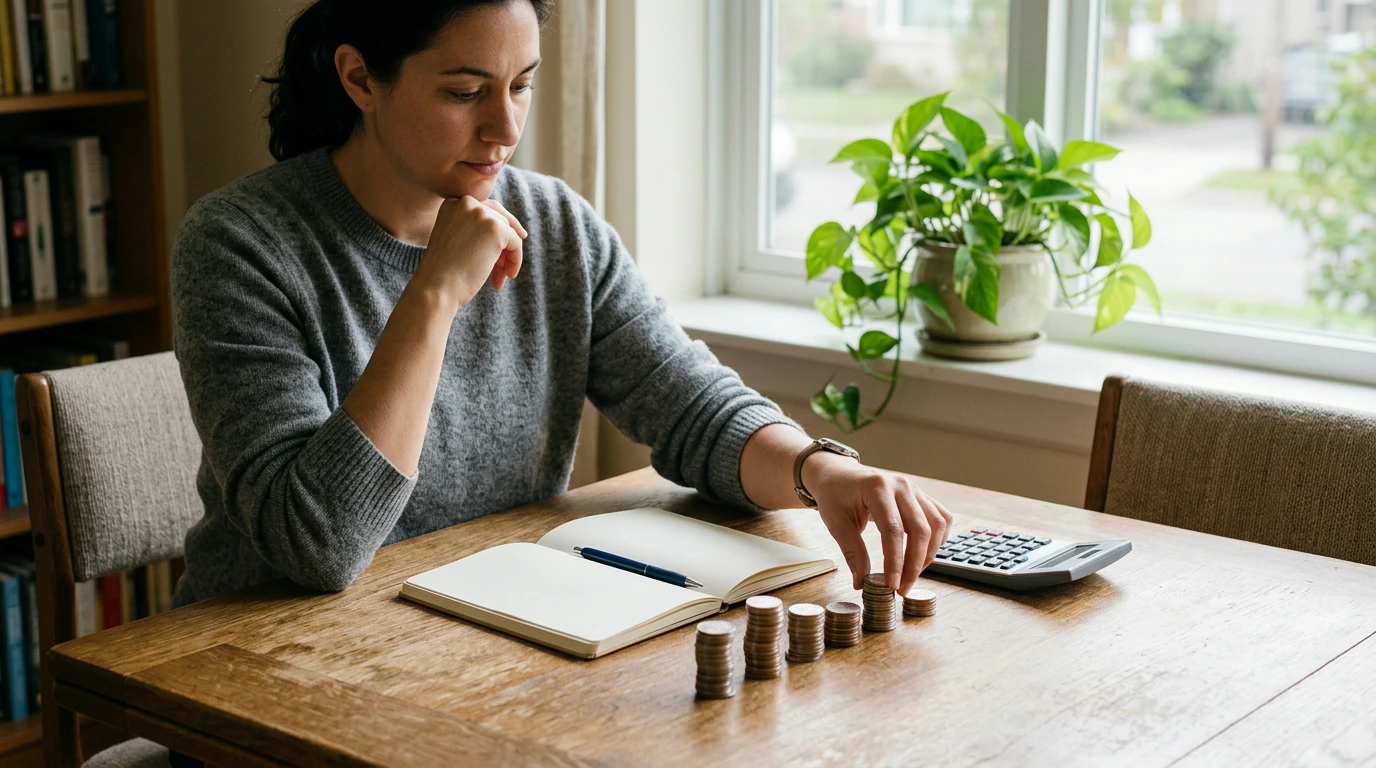
Reaching $1 million in 60 months is a bold financial goal. It can also be a useful starting point for a conversation about what you earn, save, own, and owe—even if your eventual target or timeline looks different.
Our team offers Million in Five for readers interested in exploring that ambitious goal. A resource can help you frame your thinking, but your results will depend on your circumstances and decisions, not a title or a promise.
Before making a plan, decide what the $1 million represents. A savings or investment target generally refers to the balance in the accounts you have selected for that goal. A net worth target is broader: it is the value of everything you own, minus everything you owe.
For example, a home, retirement accounts, and cash savings may count toward net worth, while a mortgage and other debts reduce it. A $1 million net worth does not necessarily mean you have $1 million available to spend.
Your starting resources, monthly contributions, investment returns, and willingness and ability to take risk all affect the path. So does the way you define the target. Write down which assets and debts you will include, whether the goal is before or after taxes, and when you want to reach it. A consistent definition makes progress easier to measure.
One way to make a large goal tangible is to divide the amount still needed by 60 months. The following benchmarks are simple arithmetic, not forecasts. They assume a steady monthly contribution and no investment returns, taxes, or fees.
| Starting amount | Target | Monthly amount over 60 months | Assumptions |
|---|---|---|---|
| $0 | $1,000,000 | About $16,667 | No investment returns, taxes, or fees |
| $100,000 | $1,000,000 | $15,000 | No investment returns, taxes, or fees |
These figures show why your starting point matters. They also show that a five-year target may require substantial income, existing assets, or both. If the monthly amount is beyond your budget, extending the timeline or choosing a smaller target can make the plan more workable.
Investing may change the calculation, but returns are not guaranteed, and you can lose money. Taxes and fees can also reduce what you keep. The Investor.gov compound interest calculator can help you explore different scenarios; its results are illustrations, not predictions.
List your income and regular expenses, then identify how much you can consistently set aside. Include debt balances and interest rates, emergency savings, and existing assets. This snapshot helps you see whether a proposed contribution fits alongside essentials and other obligations.
Consider keeping an emergency reserve for unexpected expenses rather than committing every available dollar to a long-term target. Paying down expensive debt may also be a useful priority, depending on your situation. Your plan should account for both growth ambitions and the financial pressures you could face along the way.
Break your goal into milestones you can revisit quarterly or annually. Track the amount contributed separately from changes in asset values, so you can distinguish your saving habits from market movements. Compare your progress with your budget, not just the headline target.
If income changes, expenses rise, or markets fall, adjust the contribution, timeline, or target as needed. A revised plan is not a failed plan: it can reflect better information about what is sustainable for you.
Before investing, consider how much loss you could tolerate and whether you might need the money within five years. Spreading investments across different assets can reduce some risks, although diversification cannot guarantee a profit or prevent every loss. Review investment costs as well; even recurring fees can affect the amount available for your goal. For an introduction, see Investor.gov’s guide to diversification.
If you want a resource centered on an ambitious five-year target, explore Million in Five: The Smart, Bold Path to $1M in 60 Months, listed at $10.99. You can use its central goal as an opportunity to examine your own numbers and decide which milestones make sense for you.
For a separate financial decision, we also offer Turn an Old Car Into a Smart Tax Move: A Complete Checklist for Donating Your Car to Charity for a Tax Write-Off. A donation does not automatically produce a tax benefit; eligibility and any deduction depend on your circumstances and applicable rules.
Neither resource guarantees a financial outcome or replaces individualized financial or tax advice. Consider speaking with a qualified professional when you need guidance tailored to your situation.
No. Your outcome depends on your starting resources, contributions, market performance, and other factors.
Starting from zero, you would need about $16,667 per month over 60 months, without accounting for returns, taxes, or fees. A different starting balance or investment outcome changes the calculation.
It may interest you if you want to explore an ambitious five-year financial target. Assess any goal against your own resources, obligations, and capacity for risk.

Leave a comment